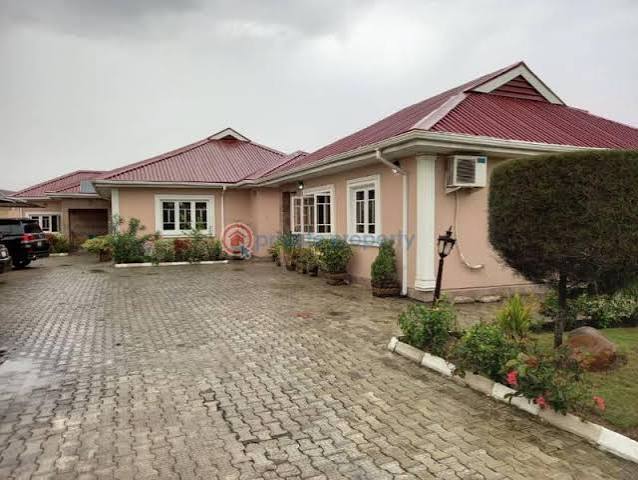
Nigeria’s deepening housing deficit, coupled with soaring land, construction and mortgage costs, is putting homeownership beyond the reach of millions of households, prompting property experts to advocate cooperative societies as a more effective vehicle for affordable housing delivery.

With Nigeria’s housing deficit estimated at more than 20 million units, experts say cooperatives can help close the gap by pooling members’ savings, acquiring land and building materials in bulk, partnering with developers and financial institutions, and spreading housing payments over longer periods.
They said the model could transform cooperatives from traditional savings-and-loans associations into structured housing platforms connecting aspiring homeowners with land, developers, mortgage finance and government-backed infrastructure.
Gbenga Ismail, a former Chairman of the Nigerian Institution of Estate Surveyors and Valuers (NIESV), Lagos Chapter, said cooperatives possessed the collective financial strength to make homeownership more attainable if properly structured and professionally managed.
According to him, cooperatives can pool members’ resources, acquire land collectively, partner with credible developers and mortgage institutions, and negotiate with government for serviced land and infrastructure.
He also advocated flexible ownership models such as rent-to-own, shared equity and phased payments, supported by strong professional management and transparent governance.
Ismail said collective purchasing power could significantly reduce the cost of land, construction and housing finance.
On the performance of cooperatives in housing finance, he said they had made important contributions but had yet to fully exploit their potential.
He noted that successful cooperative housing schemes across the country had demonstrated that the model was viable.
“The challenge is scale. Many cooperatives still operate mainly as savings and loan organisations rather than structured housing institutions. The opportunity is therefore to transform cooperatives into effective platforms connecting members, land, developers and long-term mortgage finance,” he said.
Ismail added that while individual homeownership remained difficult for many Nigerians, properly structured cooperatives could make it considerably more achievable through collective action.
Gbenga Afolayan, an estate surveyor and valuer, also called for a shift from conventional savings and loans to structured cooperative housing schemes.
He proposed that societies establish dedicated housing funds requiring members to make monthly contributions in addition to their regular savings.
Such funds, he said, should be ring-fenced for land acquisition, construction and housing finance.
“Members can build up equity over 2–5 years and acquire land in bulk. The cooperative can negotiate directly with government, estates and landowners to acquire large parcels at lower per-unit prices. Members can then receive individual plots or completed houses,” Afolayan said.
He added that bulk land acquisition could substantially reduce land and infrastructure costs.
Afolayan further advocated collective housing development rather than simply providing individual members with construction loans.
He said cooperatives could appoint reputable professionals to develop standard house types, including two-bedroom apartments, three-bedroom terraces, three-bedroom semi-detached houses and four-bedroom duplexes.
“Standardised designs can reduce construction costs. Rent-to-own housing could be particularly useful for members who cannot raise a large deposit,” he said.
Under the model, he explained, a cooperative could acquire or build a house, with the member making an initial equity contribution and occupying the property while paying monthly instalments over 10 to 20 years. Ownership would transfer after the agreed obligations had been fulfilled.
Afolayan also urged cooperatives to negotiate master financing arrangements with banks and mortgage institutions rather than leaving individual members to seek financing independently.
He said cooperatives could provide member verification, equity contributions, salary or income information and collective repayment arrangements, potentially making it easier for financial institutions to assess and finance members.
He also suggested construction-loan schemes for members who already owned land, enabling them to finance projects in stages, from foundation and blockwork to roofing, plumbing, electrical installations and finishing.
Another major opportunity, according to Afolayan, lies in bulk procurement of building materials.
Cooperatives, he said, could negotiate directly with manufacturers and major suppliers for cement, iron rods, blocks, roofing sheets, doors and windows, tiles and plumbing materials.
Collective demand, he argued, could secure better prices and reduce overall construction costs.
“For a Nigerian cooperative society, I would structure it around three membership categories namely scheme, member contribution and housing solution,” he said.
He added that the structure would provide members with different pathways to homeownership rather than assuming that every member could afford the same type of property.
Afolayan also proposed that cooperative societies establish Housing Development Companies as Special Purpose Vehicles (SPVs) for their housing projects.
Such structures, he said, would help separate housing development activities from ordinary savings and lending operations, while appropriate legal, accounting and regulatory arrangements would promote transparency and accountability.
Also, Akin Opatola, Vice President, World Council of Managers, FIABCI International, said cooperatives must move beyond their traditional savings-and-loans model and become strategic partners in housing delivery.
“Cooperative societies must evolve from savings-and-loans associations into strategic housing delivery partners,” he said.
“There is a significant difference between giving someone a loan to buy land and helping that person acquire a completed, habitable home.”
The experts’ proposals point to a broader role for cooperatives in Nigeria’s housing market, particularly as high interest rates, rising construction costs and expensive urban land continue to make conventional homeownership increasingly difficult for middle- and low-income households.
With stronger governance, professional management and partnerships with developers, mortgage lenders and government, cooperatives could provide a more collective and potentially affordable pathway to homeownership.