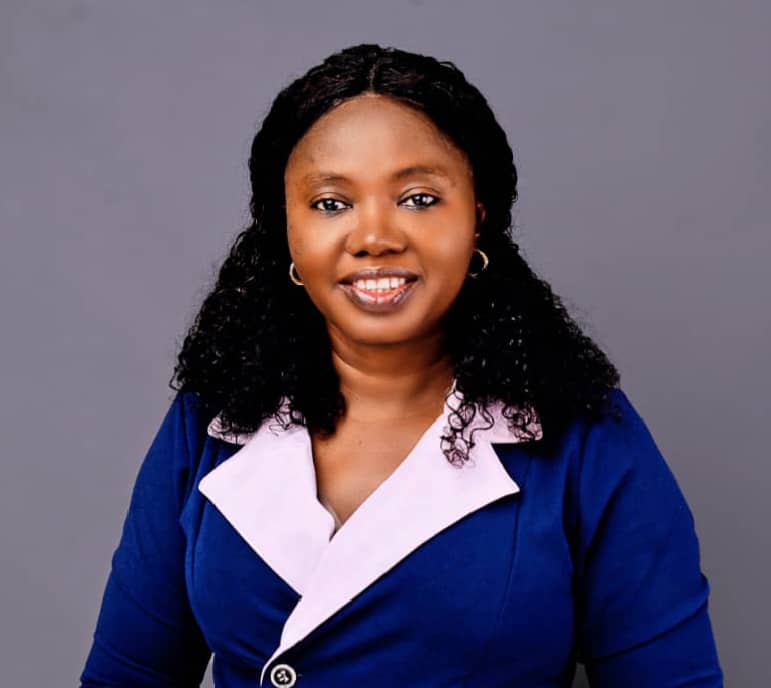
…An engagement with Lilian Ehigiamusoe, Executive Director, Operations, LAPO Microfinance Bank on the Future of Financial Operations

Operations is often seen as the engine room of a financial institution. What does operational excellence mean to you in a microfinance bank serving millions of customers?
For me, operational excellence is the discipline of turning strategy into service customers can rely on, every day and in every location. As the executive responsible for operations, I am accountable for what happens between a decision taken at head office and the experience a customer has at the counter, with an agent or on their phone. It is not simply about processing transactions faster or reducing costs; it is about designing processes that make the right thing easier, safer and more accessible for the customer and for the staff who serve them.
That matters because of the scale and diversity of the people we serve. We operate across more than 500 branches in 34 states and the FCT, serving millions of customers with different financial needs. My test is consistency: a customer in a rural branch should receive the same standard of service, the same turnaround and the same protection as one in a city. The real measure of operational excellence is therefore not the size of the network. It is how effectively that network converts reach into access, access into usage, and usage into meaningful financial outcomes.
LAPO MFB has built its reputation around last-mile financial inclusion. How do you maintain that physical reach while the industry is becoming increasingly digital?
I do not see physical and digital channels as competing models. From an operations standpoint they are parts of the same customer journey, and my job is to make them work as one. Digital banking can remove friction, improve convenience and make transactions available beyond traditional banking hours. But for many financially underserved customers, especially micro-business owners and people in rural and semi-urban communities, the human relationship remains important.
That is why our approach is increasingly hybrid. LAPO MFB combines its extensive physical network with digital channels, agents and technology-enabled services. The operational work lies in the joins between them: service standards should be the same whichever route the customer takes, and a problem should be resolved without the customer having to work out which channel owns it. Our objective is not simply to move customers from branches to digital platforms; it is to give customers the freedom to choose the channel that works best for them. The question I ask is not branch or digital? It is: how do we make every customer interaction simpler, safer and more productive, regardless of the channel?
What role does data play in improving operations and customer experience?
Data is increasingly the connective tissue between strategy, operations and customer experience. In operations, we use it to see where customers experience friction, where processes slow down, where demand is changing and where operational risks may be emerging. But data only earns its place when it leads to action. A high transaction volume, for example, does not automatically mean a successful channel. I want to see completion rates, turnaround times, repeat usage, complaints, failed transactions and customer behaviour, because those are the measures that tell me whether a process is actually working for the customer.
The discipline I push for is that every operational report should end in a decision: a process to fix, a control to tighten, a branch to support. I believe the future of operations will be defined by the ability to move from descriptive data (what happened) to diagnostic and predictive intelligence (why it happened and what we should do next). That shift allows us to intervene before a service failure reaches the customer, rather than after
LAPO MFB has millions of customers and a large branch network. How do you balance growth with operational control?
Scale without control creates fragility. Control without innovation creates stagnation. My responsibility is to build an operating model in which growth and control reinforce each other, so that every new branch, product or customer segment is added onto processes that can carry the load. That requires clear and standardised processes, strong governance, effective monitoring and accountability at every level, from head office to the branch.
Risk management is particularly important in microfinance because our operating environment involves large volumes of relatively small transactions, geographically dispersed customers and increasingly digital touchpoints. A small process weakness, repeated across hundreds of locations, quickly becomes a material one. So I do not view risk management as an obstacle to growth. Good controls enable sustainable growth because they allow the institution to take calculated risks with greater confidence.
Digital finance has expanded access, but it has also introduced new operational and fraud risks. How should financial institutions respond?
The digital transformation of financial services has changed the risk equation. Technology risk, fraud, data protection, third-party risk, customer behaviour and operational resilience can no longer be managed as separate issues; they are interconnected, and operations is where they meet. My view is that prevention must be designed into the operating model rather than added after a loss. In practice, that means building controls into the process itself, monitoring for unusual patterns, continuously educating customers and employees, and ensuring that technology, risk, operations and business teams work together rather than in sequence.
When an incident does occur, the speed and fairness of our response matter as much as the control that failed, because that is the moment a customer decides whether to keep trusting us. My own professional development in digital finance and risk has reinforced an important lesson: you cannot scale digital financial services responsibly without scaling the risk-management capabilities around them.
Customer experience is increasingly becoming a differentiator in financial services. What does customer-centric operations look like in practice?
Customer-centricity should be visible in the process, not just in the slogan. In operations, that is something we can design and measure.
It means asking: How many steps does the customer have to take? How long does it take? How many times do they have to provide the same information? What happens when something goes wrong? How quickly can we resolve it? Each of those questions points to a process that someone in operations owns and can improve. That is why I measure customer experience through outcomes e.g. turnaround time, service reliability, complaint resolution, accessibility, repeat usage and, ultimately, customer trust.
LAPO MFB has continued to expand its digital proposition. What operational changes are required to support this transition?
Digital transformation is not a technology project; it is an operating-model transformation, and much of that work sits in operations. When you introduce a digital product, you are changing how customers interact with the institution, how employees work, how transactions are monitored, how risks are managed and how service failures are resolved. Each of those has to be ready on the day the product goes live, not afterwards.
As a bank, our digital journey therefore requires investment not only in platforms but also in processes, people, data, controls and customer education. Our mobile banking proposition, for instance, is part of a broader effort to make savings, payments and lending more accessible. Its success depends as much on what happens behind the screen customer support, issue resolution, staff who can guide a first-time user as on the app itself.
The ultimate test is simple: does technology make banking easier without compromising trust?
Financial inclusion is often measured by the number of people reached. Is reach enough?
No. Reach is the beginning of inclusion, not the end of it. A person having an account does not necessarily mean that person is financially included in a meaningful sense. From where I sit, an opened account is a starting point, not a result. We should be asking deeper questions: Are customers actively using formal financial services? Are they saving? Can they access appropriate credit? Are they building resilient businesses? Are they able to manage financial shocks?
For LAPO MFB, this is especially relevant because our customer base includes micro and small businesses, women entrepreneurs, farmers and low-income households. Our purpose is not simply to put financial products in their hands; it is to make those products useful to their economic lives. Much of that usefulness is decided in operations: whether the service is close by, available when the customer needs it, simple to use and dependable.
That is why I believe the next frontier of financial inclusion is quality of access not just quantity of access.
LAPO MFB has reported more than ₦1.7 trillion in cumulative lending to MSMEs. What does a number like that mean from an operations perspective?
A number of that magnitude represents both impact and responsibility. LAPO MFB has reported cumulative microloan disbursements of more than ₦1.7 trillion to MSMEs since inception. Behind that figure is a very large number of individual loans, each of which had to be processed accurately, on time and under proper controls. From an operations perspective, that is the real story. The operational question is what happens around each loan: Does the customer receive the right amount at the right time? Is repayment structured around the realities of the business? Can the customer access subsequent financing as the business grows? Are we protecting customers from inappropriate borrowing?
This is why responsible lending must sit alongside financial inclusion. The objective is not simply to increase the volume of credit; it is to ensure that credit creates productive economic activity without creating unsustainable indebtedness. Operations is where that commitment is kept, one transaction at a time.